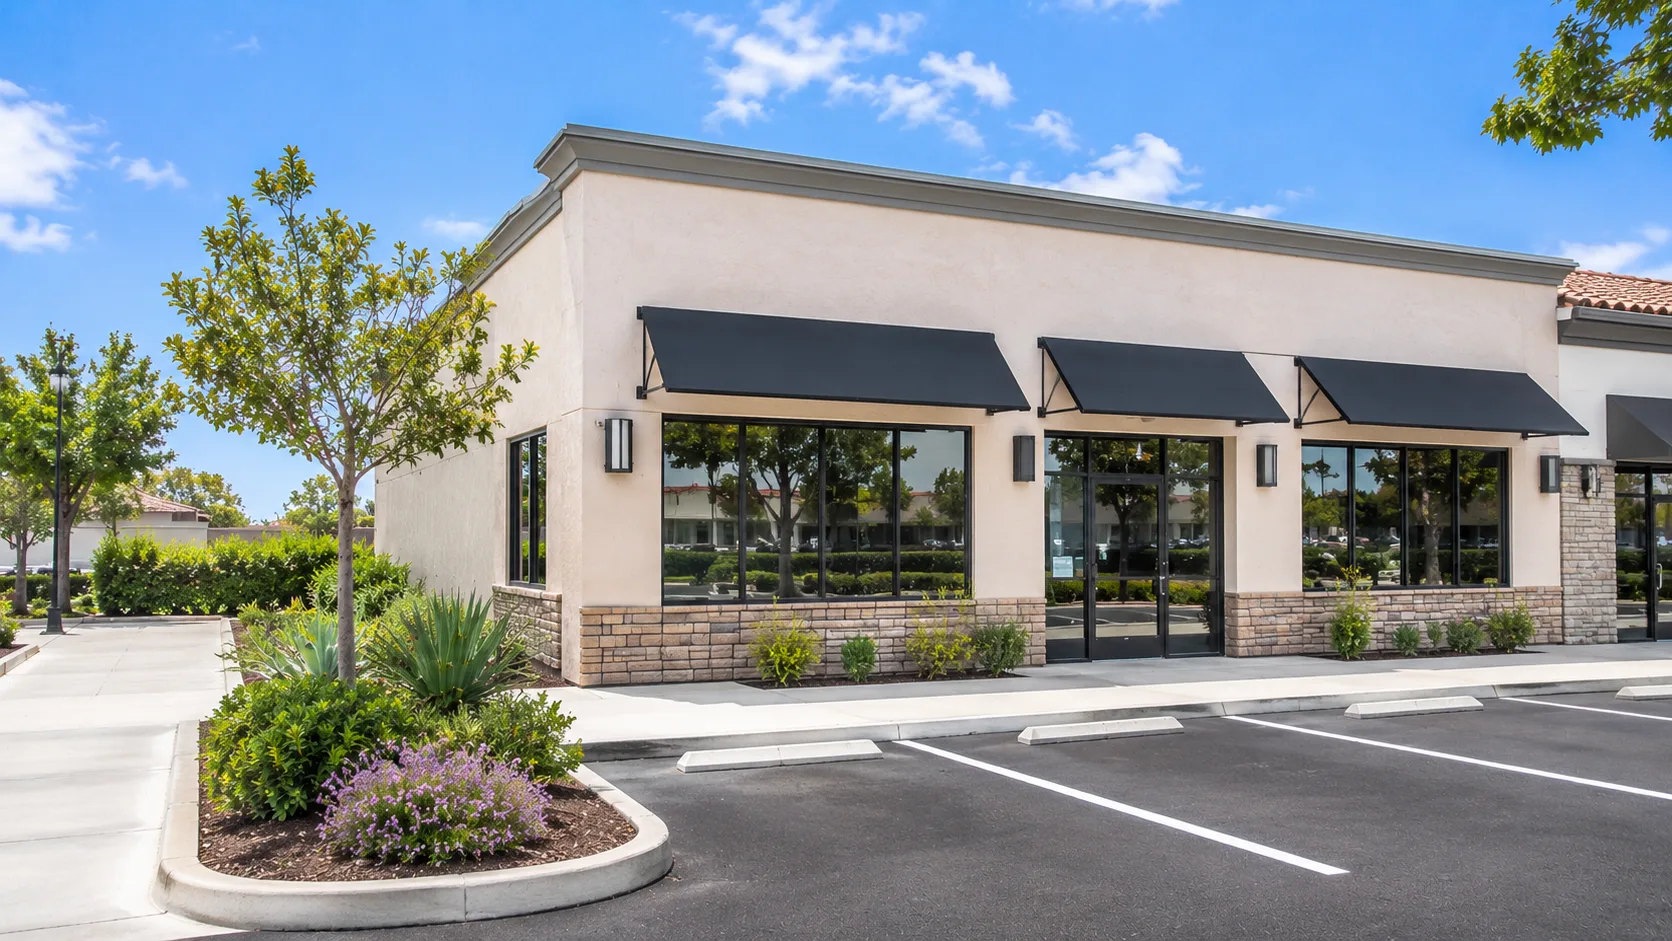
Santa Ana, CA commercial financing
Commercial Property Loans in Santa Ana
Send us the building and the plan, and we'll put it in front of our capital partners.
Get a Free Quote for Commercial Property Loans
Commercial Property Loans in Santa Ana, Built Around the Building
Santa Ana's industrial corridors near the 55 and 5, its older retail strips along Main and Bristol, and the mixed-use blocks downtown give investors plenty of buildings worth owning and plenty that need work first. Commercial property loans in Santa Ana are short-term, asset-based loans that look hard at the building, its location and your plan for it. Your tax returns matter less than they would at a bank.
That focus is what makes them useful when timing is tight. Maybe a seller wants a quick close on a tired office building, or a vacant shop needs new tenant improvements before a bank will touch it. We read through the deal, then send it to lenders who work with that property type, so you hear where you stand sooner. Tell us what you're buying and what you plan to do with it. Get a free quote →
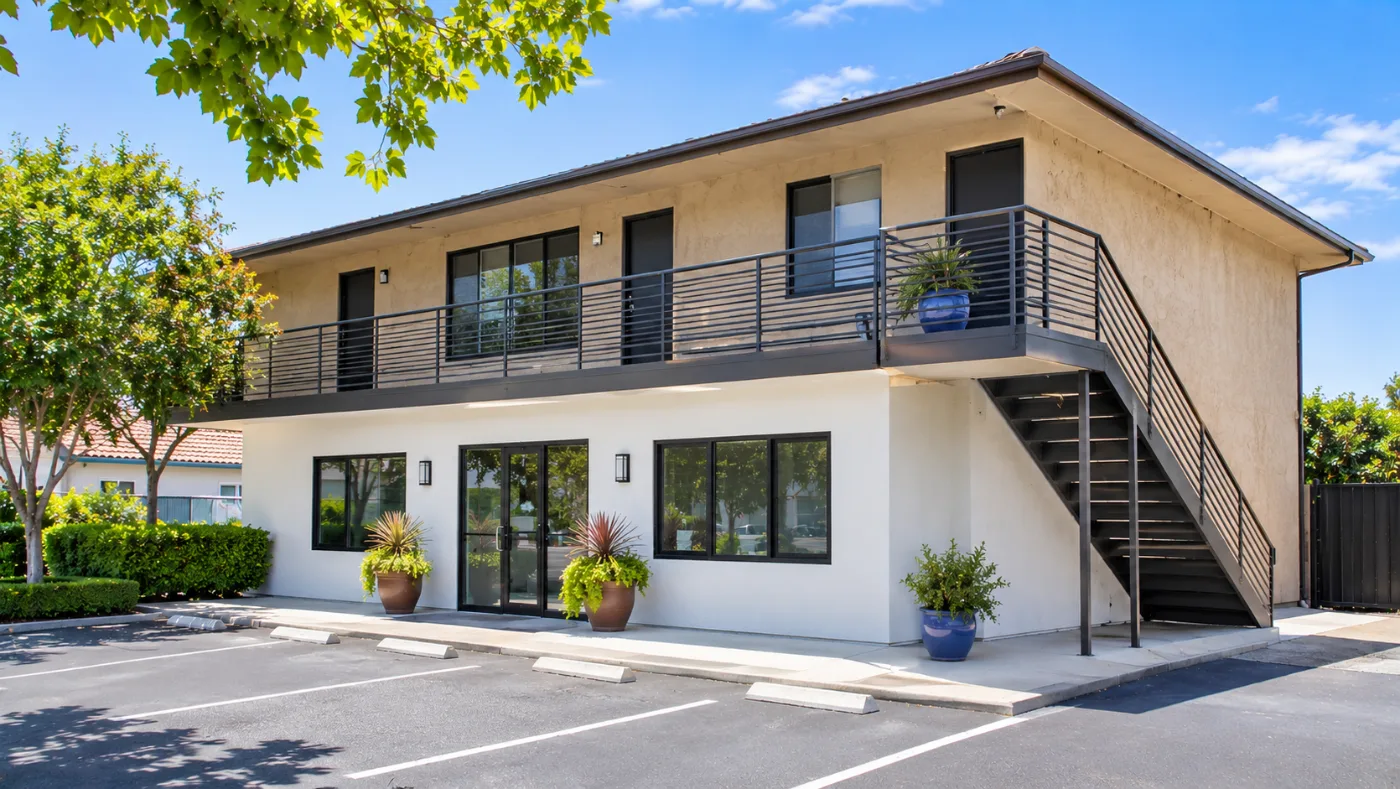
How Commercial Deals Work in Santa Ana
The property type shapes the loan more than anything else. Lenders in this space commonly finance retail, small office, light industrial, warehouse, mixed-use and multifamily buildings of five units or more. A fully leased building with steady rent is a different conversation from a half-empty one, and lenders price them differently.
Loan size and leverage follow the asset. Typical commercial bridge-style loans in the market run from the low six figures into the millions, often up to roughly 65 to 75 percent of value, with terms commonly between 6 and 24 months. Lenders usually weigh the building's condition, occupancy and location, plus your plan to refinance or sell.
Your exit plan gets as much attention as the purchase. Most investors use a short-term loan to buy, fix up or lease up a building, then move into longer-term bank or agency financing once it's stabilized. If the lease-up runs slower than planned, extensions are something to ask about before you sign, not after.
Local details matter too. Santa Ana's zoning, including the downtown Renaissance area and the industrial districts, decides what uses are allowed, and a change of use or tenant improvements go through the city's permitting process. Check the zoning and any open permits early, because they can change both the timeline and what a lender will advance.
Retail and Mixed-Use Buildings
Storefronts with apartments above and neighborhood retail strips are common in and around downtown. Lenders look at tenant mix, lease terms and how much of the building is occupied.
Light Industrial and Warehouse
Santa Ana's industrial pockets draw buyers who want flex space, small warehouses and shop buildings. Loans here often hinge on clear access, condition and a realistic plan for tenants.
Small Office Buildings
Older office buildings can be good value-add plays if you have a plan for updates and leasing. Expect lenders to ask how you'll fill vacant suites and what the building will be worth once you do.
Value-Add and Vacant Properties
Buildings that a bank won't finance because they're partly empty or need repairs are a common fit for short-term loans. The lender will want to see your budget, timeline and how you'll exit.
What Commercial Property Loans Typically Cost
| Cost item | Typical range | What affects it |
|---|---|---|
| Interest rate | Often about 9% to 13% a year, interest-only | Property type, leverage, occupancy and your experience |
| Origination points | Commonly 1 to 3 points | Loan size and deal complexity |
| Loan term | Usually 6 to 24 months | Scope of work and how long lease-up takes |
| Third-party fees | Appraisal, legal, title, insurance and inspections | Property size, environmental needs and title history |
These are typical market ranges for planning, not quotes, and actual terms depend on the lender and the deal.
Why Choose Us for Commercial Property Loans?
We start with the building
We look at the property, the lease situation and your exit before anything else, so the lenders we suggest actually fit the deal.
Local context included
We know how Santa Ana's zoning, older building stock and permitting can affect a commercial timeline, and we say so up front.
Straight talk on tradeoffs
Short-term money costs more than a bank loan. We'll lay out when that cost is worth the speed and when a slower option makes more sense.
How It Works, Step by Step
Share the property details
Send the address, purchase price or current value, the condition and your plan for the building.
We read the deal
We look at occupancy, zoning, budget and exit so we know where to place the deal.
Compare lender options
You see the typical terms our capital partners offer for your property type.
Lender review and appraisal
The lender you choose reviews the file and orders valuation, title and any other third-party reports.
Close and execute your plan
Once the lender approves and documents are signed, you close and move on to renovation, leasing or your refinance.
Commercial Property Loans Across Santa Ana, CA
Ready to Get Started?
Have a Santa Ana building in mind? Give us the details and we'll lay out your options.